
1. Acquisition
Buying the property or site.
Buying the site is one step. Funding the works is another. Getting from purchase to completion without running out of time or capital is the real job. WeFinance UK helps developers structure property finance around the project from acquisition through to exit
Typical project
Refurbishment, conversion or development
Funding stages
Acquisition, works and exit
Key numbers
Cost, value, contingency and timing
Approach
Start with the full project
The finance may depend on: • purchase price • current value • development costs • professional fees • contingency • planning status • project experience • build programme • expected completed value • exit strategy • developer contribution
The stronger those elements are understood, the easier it becomes to judge which funding structure is realistic.
A project may use different finance at different stages.
Buying the property or site.
Funding works needed to create the finished asset.
More substantial construction or redevelopment.
Sale, refinance onto long-term investment finance or another agreed repayment route. The exit should not be an afterthought.
Get started →The total facility and the cash available on day one are different figures. Development funding is often released in stages, with further advances subject to progress checks and the lender’s drawdown conditions. Your cashflow plan needs to show when you must pay contractors and professional fees, when funding is expected and how you will cover any gap. Alongside your deposit or equity contribution, allow for surveys, planning, legal and lender fees, interest, monitoring costs, holding costs and contingency. The project needs enough working capital to keep moving between drawdowns, not simply a loan large enough on paper.
A project that works with no contingency is not automatically a well-funded project.
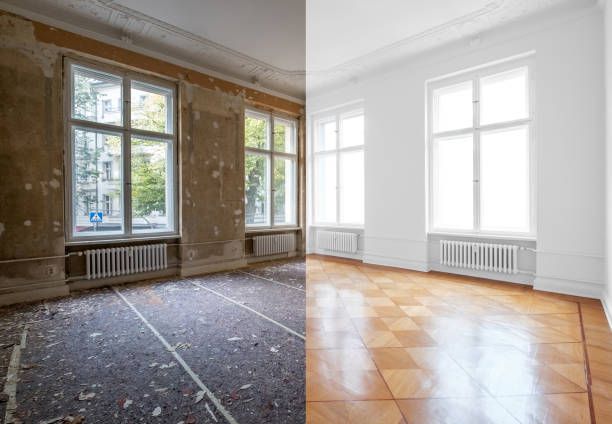
Projects can range from relatively light improvement to substantial structural works or a change in configuration. The level of works can affect the finance route. Examples might include: • standard refurbishment • conversion to HMO use • creating additional units • commercial to residential conversion where permitted • major internal reconfiguration • extension • structural work
The lender needs to understand what the property is today and what it is expected to become.
Developer experience can influence lender appetite. A first development does not automatically mean finance is unavailable, but the professional team, project complexity, cash position and experience of those carrying out the work may receive greater scrutiny. The deal needs to be presented honestly.
That depends on the project, borrower, lender and relevant loan-to-cost or loan-to-value limits.
Potentially. If the finished property will be retained, the future long-term mortgage should be considered before the development loan is agreed.
Time affects interest, loan term and potentially the exit. A realistic programme and contingency matter.
We want to understand: • purchase • works • timing • costs • contingency • experience • planning • completed value • exit Then we look at the finance.
Send us the numbers and the exit.